Yann Furic
B.B.A., M. Sc., CFA®
Senior Portfolio Manager, Asset Allocation and Alternative Strategies
After a turbulent end to the summer marked by skyrocketing tariffs and economic instability, September 2026 was in turn characterized by persistent geopolitical tensions, rising budget deficits and a steady increase in interest rates worldwide.
A positive global outlook despite everything
The global growth indicator of the Organization for Economic Cooperation and Development (OECD) continues to forecast growth of 3.1% in 2027, which is positive. Global PMI indicators remained in expansionary territory and even improved slightly worldwide, despite a decline in some Southeast Asian countries.
Corporate earnings, which met expectations in the second quarter, will once again come under close scrutiny starting the week of October 12. Earnings growth of 29.5% for the S&P 500 index is expected for this final quarter, compared to the same period in 2025. As for the S&P/TSX Canadian Index, growth is expected to be 23.9%. This strong increase in earnings is allowing stock markets to hold steady and even rise, despite rising interest rates.
Against this backdrop, stock markets continue to benefit from a boom partly driven by infrastructure spending for the development of artificial intelligence (AI). Economic growth, though modest, is spreading to several sectors, which is positive for the markets.
Government bond yields
Since the beginning of the year, 10-year yields have been rising due to inflation and budget deficits. While yields on Japanese, German and Canadian bonds have followed a similar trend, U.S. and French bonds have seen more significant yield increases since the end of August.
In France’s case, chronic deficits and a government deadlock preventing the passage of a budget are weighing on yields, which are now significantly higher than German yields—the benchmark in Europe.
In the United States, an above-target inflation rate and a significant deficit—even though the country is not in a recession—are having a direct effect on the yield investors are demanding to finance the government.
Global Yields on 10-Year Government Bonds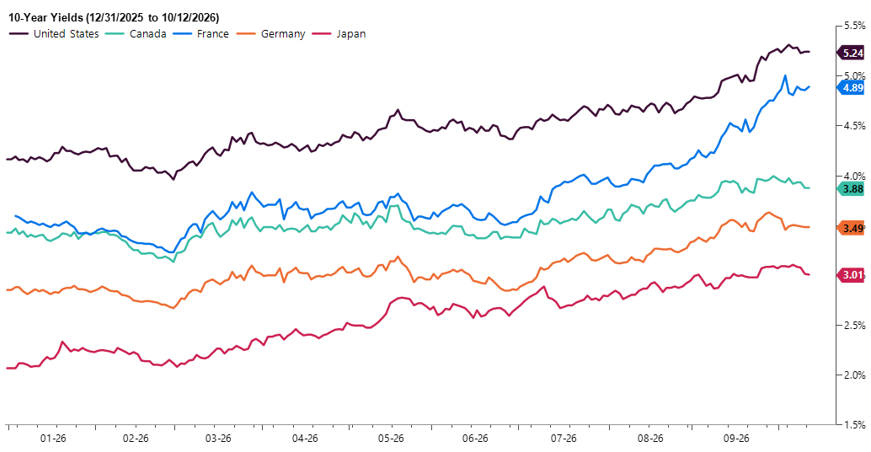
Key issues: inflation and energy, once again
Persistent inflation in the United States and the impact on energy prices caused by the conflict with Iran are keeping price growth too high. Several central banks have either resumed raising rates or are seriously considering doing so. Accelerating job losses in Canada could prompt its central bank to put any further rate hikes on hold.
Efforts to minimize the impact of the conflict with Iran on the transport of petroleum products through the Strait of Hormuz and throughout the region appear to have restored about 85% of the volumes that were transiting at the beginning of the year, but the significant increase in marine insurance costs and the use of less efficient alternative routes are keeping prices high.
The recent attacks on Saudi infrastructure by Iran-linked groups are aimed at increasing that country’s bargaining power vis-à-vis the United States, because the resumption of oil tanker transit through the Strait of Hormuz and the use of other alternative routes have shifted the balance of power between the two adversaries. Several European countries have also agreed to tap into their strategic reserves to lower energy prices for freight transport and to meet the needs of their citizens.
Despite this, the price of diesel remains high. This fuel is used primarily in the agricultural and transportation sectors; the impact of the soaring costs is therefore significant in terms of inflation. The agreement between the United States and Russia to import Russian diesel could temporarily lower the price of this fuel, but the deal violates a law passed in 2022 by the U.S. Congress. The coming weeks will shed more light on how this situation unfolds.
U.S. midterm elections
On November 3, one-third of the U.S. Senate and the entire House of Representatives will be up for election. The markets are anticipating a victory for the Democrats, who are expected to win a majority in the House of Representatives.
A Democratic majority in the Senate could also lead to a mixed reaction, with some positive and some negative elements, but even in that case, neither party would have the required majority of 60 senators needed to move legislation forward quickly. In such a context, and after some time, corporate profits and future growth would rebound. It should also be noted that, historically, the third year of a presidential term (the one following the midterm elections) is usually a positive period for the stock markets.
The scenario no one is talking about is one in which the Republicans retain majorities in both Houses. The current administration could then view this victory as a validation of its strategy and push forward an even more extensive tariff plan.
Jobs: losses and gains
Job creation in Canada was weaker than expected, with a loss of 68,300 jobs, mainly in the public sector, among both full-time and part-time workers. The private sector added 24,100 jobs. Quebec saw the highest job losses, with 49,400 jobs cut. Previously, August had seen a loss of 41,700 jobs, mainly full-time positions. The gains made in June and July were thus completely wiped out. The recent tariff dispute also played a role in the loss of 12,700 manufacturing jobs. Wage growth rose from 2% to 2.3%.
South of the border, the employment situation was positive, with 29,000 jobs added—well below expectations of 90,000. The previous month’s data were also revised downward, from 162,000 jobs added to 133,000. For several months now, the United States has been experiencing stable but weak job growth. Overall, wage inflation at 3.0% and a stable job market are factors militating in favour of a rate hike by the U.S. Federal Reserve (Fed) by the end of the year.
U.S.-Iran conflict: nothing has been resolved yet
The conflict between the United States and Iran continues to make daily headlines. The price of oil remains the key indicator of the conflict’s status.
The U.S. administration has indicated that it will not escalate the conflict before the midterm elections.
Financial market performance last month
OVERVIEW OF GLOBAL EQUITY MARKETSAll percentages are in Canadian dollars. |
||||
|
Country |
Index |
Return* |
Change |
Year-to-date return in 2026 |
|
Canada |
S&P/TSX |
-2.62% |
|
12.97% |
|
United States |
S&P 500 |
2.06% |
|
16.78% |
|
|
Nasdaq |
4.38% |
|
20.24% |
|
International stock markets |
EAFE |
-0.71% |
|
14.28% |
|
Emerging markets |
|
1.84% |
|
27.79% |
|
China |
MSCI China |
-2.27% |
|
-8.71% |
*The return shown is the total return, which includes the reinvestment of income and capital gains distributions
Source : Morningstar Direct.
RETURN ON CANADIAN BONDS |
|
| Index | Return from January 1 to September 30, 2026 |
| FTSE Canada Universe Bond Index | 0.78% |
Source : Morningstar Direct
Data influencing the markets
CANADA |
UNITED STATES |
Recession Indicator |
|
Moderate |
Moderate |
Policy Rates |
|
2.25% |
3.50% – 3.75% |
|
No change was announced by the Bank of Canada on September 2, 2026. The BoC remains optimistic about GDP growth in 2026. |
The U.S. Federal Reserve raised its policy rates on September 16, 2026. Uncertainty surrounding inflation and employment persists and is compounded by inflationary pressures stemming from the conflict with Iran. The market is anticipating another rate hike in December. |
Employment Situation |
|
|
Jobs lost: 68,300 Expectations: gain of 10,000 |
Jobs gained: 29,000 Expectations: gain of 90,000 |
|
|
|
|
Wage growth: 2.3% Expectations: 2.3% |
Wage growth: 3.0% Expectations: 3.1% |
|
Unemployment rate: 6.5% Expectations: 6.5% |
Unemployment rate: 4.2% Expectations: 4.1% |
Inflation |
|
|
August: 3.1% Change: 0.1% |
August: 3.7% Change: 0.0% |
Overall, what are the economic indicators telling us?
Benchmark rates (Canada, Europe and the United States) 
- U.S. Federal Reserve: upward pressures, but likely a pause at the October 28 meeting so as not to be accused of interfering with the midterm elections.
- Bank of Canada: no change in rates, with close monitoring of the consequences of the conflict in Iran. A possible rate hike by year end.
- European Central Bank (ECB): rate increase at its September meeting and awaiting future economic data. Expectations of one rate hike for the rest of the year due to the conflict in Iran and its impact on energy prices.
Global Purchasing Managers’ Index
- Manufacturing segment: positive, with 22 of the 30 countries in this segment posting a reading above 50 (expansion).
- Services segment: continues to hold up.
- Global inflation rate: fears of rising inflation due to the conflict with Iran and energy prices. General trend: no change or an increase in rates.
Factors to watch
- Conflict with Iran: The global tensions it is causing, and especially the impact on traffic in the Strait of Hormuz, will have an impact on corporate earnings. The longer the conflict drags on, the greater its repercussions will be, but supply chains are increasingly adjusting.
- Deregulation in various industries in the United States: This should help maintain economic growth and encourage investment. Other countries, such as Canada, will have to follow suit or risk losing competitiveness.
- Trade tensions: Supported by the indiscriminate use of tariffs, they could cause an economic slowdown and increase inflation, resulting in an episode of stagflation, the most negative economic scenario. The trade agreement between Canada, the United States and Mexico (CUSMA) is now in the annual renegotiation phase, which could create a climate of uncertainty in terms of corporate investment.
- Inflationary scenarios: If they result in keeping yields on five-to-ten-year maturities at high levels, they should be avoided at all costs, as they would slow business investment and the reshoring of production lines to the United States. This seems to be increasingly reflected in global yield curves.
- Geopolitical uncertainty: Conflict between the United States and Iran, the Russia-Ukraine war, regional conflicts in the Middle East, tensions between the U.S. and China, possible annexation of Taiwan by the Chinese government, return of the Monroe Doctrine in the United States.
fdp tactical views – August 2026
- We reduced the equity weighting in the tactical allocation strategy. We remain overweight stocks, but the rise in bond yields over the past several weeks has made bond returns more attractive.
- Economies continue to grow. Large companies are generally reporting solid earnings, which is keeping stock markets in positive territory. This profit growth is helping stock markets hold steady, despite the overall rise in medium- and long-term interest rates.
- In the fixed income component, we increased our holdings of North American and emerging market bonds.
We continue to favour stocks in developed countries and focus on risk management.
To learn how our funds performed:
Senior Manager, Asset Allocation and Alternative Strategies
Data source : Bloomberg
The opinions expressed here and on the next page do not necessarily represent the views of Professionals’ Financial. The information contained herein has been obtained from sources deemed reliable, but we do not guarantee the accuracy of this information, and it may be incomplete. The opinions expressed are based upon our analysis and interpretation of this information and are not to be construed as a recommendation. Please consult your Wealth Management Advisor.